Key Takeaways:
- When markets dip or swell outside normal ranges—reducing or increasing assets in unexpected ways—board members may feel tempted to react and reevaluate the organization’s baseline spending policies. Depending on the circumstances, straying from predefined spending policies may be a good idea for some organizations. What’s key is to understand both the long- and short-term impacts of any potential change, and that can be difficult to do in the moment.
- To better prepare for volatile market behavior, CAPTRUST recommends running stress tests to model different scenarios when establishing spending policies. What will the organization do if a market rally creates a 20 percent asset growth in one year? What will it do if a market pullback reduces asset value by the same amount?
- In these cases, for some organizations, creating conditional spending policies with provisions beyond the core distribution target for each asset pool may make sense.
Click HERE to go directly to a downloadable one-page document about common spending policy types and how to align spending policy with institutional needs.
For those who are involved in making spending policy decisions, here are a few best practices and examples to consider when designing conditional spending policies:
Integrate Conditional Spending Policies into Your IPS, and Review Regularly
A conditional spending policy is designed to encourage an organization to think proactively, not reactively, says Wally Terrell, senior specialist on CAPTRUST’s asset and liability team. “If certain conditions happen in the market, like outsize gains or the recent dip in both stocks and bonds, then spending is adjusted based on pre-planned conversations. This way, board members can be sure they’re not making knee-jerk reactions without considering the long-term perspective.”
Modeling assists decisionmakers in understanding how different events can affect the organization, and how the organization will react. It also helps ensure the team is aware of—and comfortable with—spending policy implications to its portfolio and mission.
It is important to keep in mind that adding conditional spending policies to an investment policy statement (IPS) does not mean the organization will be locked into these provisions. Conditional spending policies simply become another part of the organization’s comprehensive investment strategy, named within the IPS alongside other portfolio parameters and strategic principles, such as the organization’s investment objectives, constraints, and reporting requirements.
As a best practice, the IPS should be reviewed at least annually and any time there is a material change in the organization’s circumstances. As Grant Verhaeghe, institutional portfolios practice leader at CAPTRUST, explains, “When a triggering event occurs, board members can confirm in committee meetings whether the decision made in anticipation of this event is still the one they continue to believe is the right course of action, or not.”
There is nothing suggesting that the organization can’t change course, so long as it follows applicable tax codes, honors donor intent, and aligns with legal compliance in the context of long-term objectives.
Create Overlap Between Spending and Investments
Another best practice is to integrate the organization’s spending and investment policies by creating overlap in the teams that design them. Ideally, the people who are making spending decisions will be some of the same people on the investment committee so that both groups are aware of what is happening in both areas.
“At a minimum, the IPS ought to reference the spending policy, if they are separate documents,” says Verhaeghe. “Organizations might also consider creating a single document that encompasses both policies. Beyond that, it’s even better if an organization can create overlap between the committees that are making these decisions, because overlap creates better information and leads to better financial decisions.”
Terrell agrees: “Allocation decisions should be codified in the organization’s IPS, and everything should revolve around the mission. Spending policy, investment policy, the mission—they should all be in harmony.”
Customize the Plan to Mitigate Your Risks and Meet Your Needs
Although planning itself is a consistent best practice, there is no fixed way to establish a spending policy. Every organization is unique, which means every IPS will be unique, and the conditional spending policies included in that IPS can be infinitely customized. “There is so much flexibility,” says Terrell. “The key is to think about the organization’s unique mission and how its assets support that mission.”
As Verhaeghe explains, “The right spending policies will depend on how the organization utilizes each pool of assets for its ongoing needs.”
In other words, committee members need to understand the organization’s financial vulnerabilities and how different market conditions will impact its mission. For example, some foundations rely heavily on one asset pool, while others depend on grants and donations. The latter will have more flexibility to take investment risks but will also likely see donations decline while markets are down.
Terrell says one widespread practice is to apply different spending policies to each asset pool. For instance, he says, it’s common to have asset pools that function as reserves. Typically, these funds are invested conservatively and may grow slowly over time. In this case, Terrell says, “The foundation may decide to institute a conditional spending policy that says ‘When assets in this pool exceed a certain amount, the organization may institute a simple spending policy. But if assets do not reach the target, there is no spending from this pool whatsoever.’”
One of the more unusual types of IPS spending policies Terrell has seen is from a client that has, essentially, a growth portfolio and a separate, capital preservation portfolio with a more conservative investment strategy. “Their policy is that if the equity markets decline by more than 10 percent, then instead of distributing from the bigger, growth-focused portfolio, they would instead spend from the more conservative portfolio,” he says. “This way, they don’t unnecessarily deteriorate their equity assets and can use the market downturn as an opportunity to become more tactically aggressive than they otherwise would be under normal spending behaviors.”
Verhaeghe elaborates: “It’s like saying, ‘I don’t want to sell growth assets in a distressed environment.’ Their spending policy means they can hold onto growth assets when market valuation is better.”
As examples of how market conditions may influence mission-centered spending behaviors, Terrell and Verhaeghe offer three case studies for consideration. Note that these examples do not consider regulatory spending requirements that apply to some nonprofits, nor are they meant to serve as ready-made examples for adoption. The right conditional spending policies for each endowment or foundation will depend on that organization’s unique goals and circumstances.
Example A: Spending Floors and Ceilings
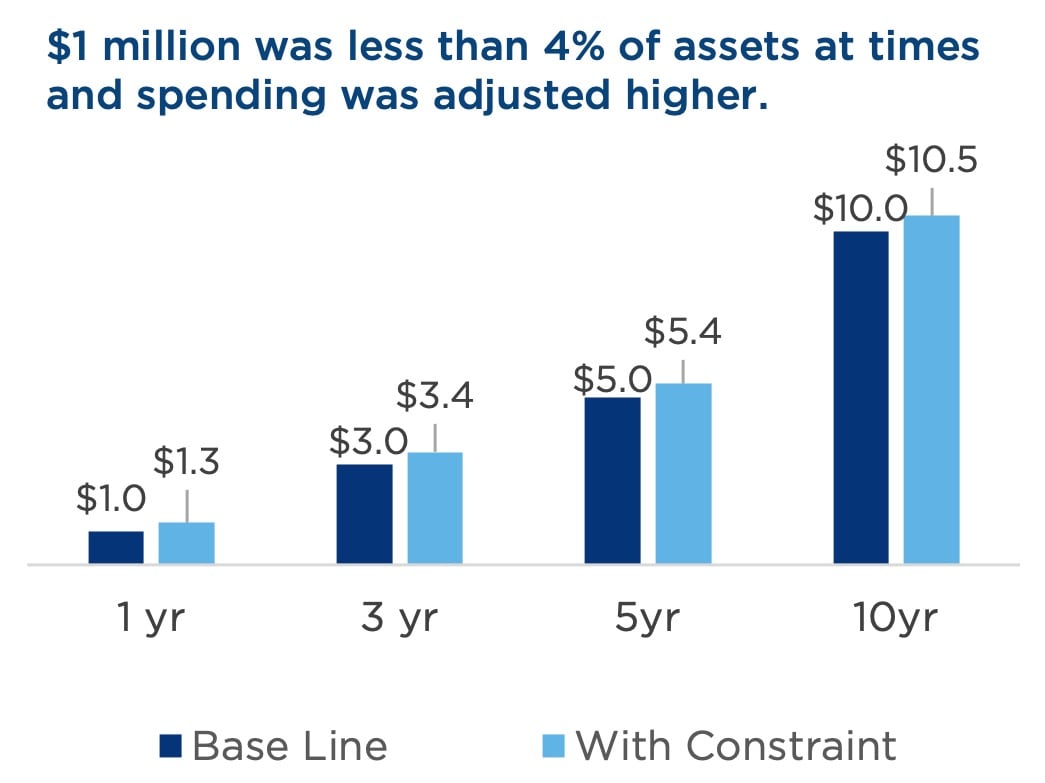
An organization may choose a flat dollar spending target, such as $1 million per year, and an additional constraint that restricts the dollar value to a minimum of 4 percent and a maximum of 6 percent of assets. While $1 million is the annual spending goal in this example, if, in a particular year, conditions result in a $1-million spend equaling less than 4 percent of assets, then distributions would be adjusted higher. The inverse would be true for a spending ceiling: If conditions result in $1 million equaling less than 6 percent of assets, then distributions would be adjusted lower.
Example B: Portfolio Valuation Date
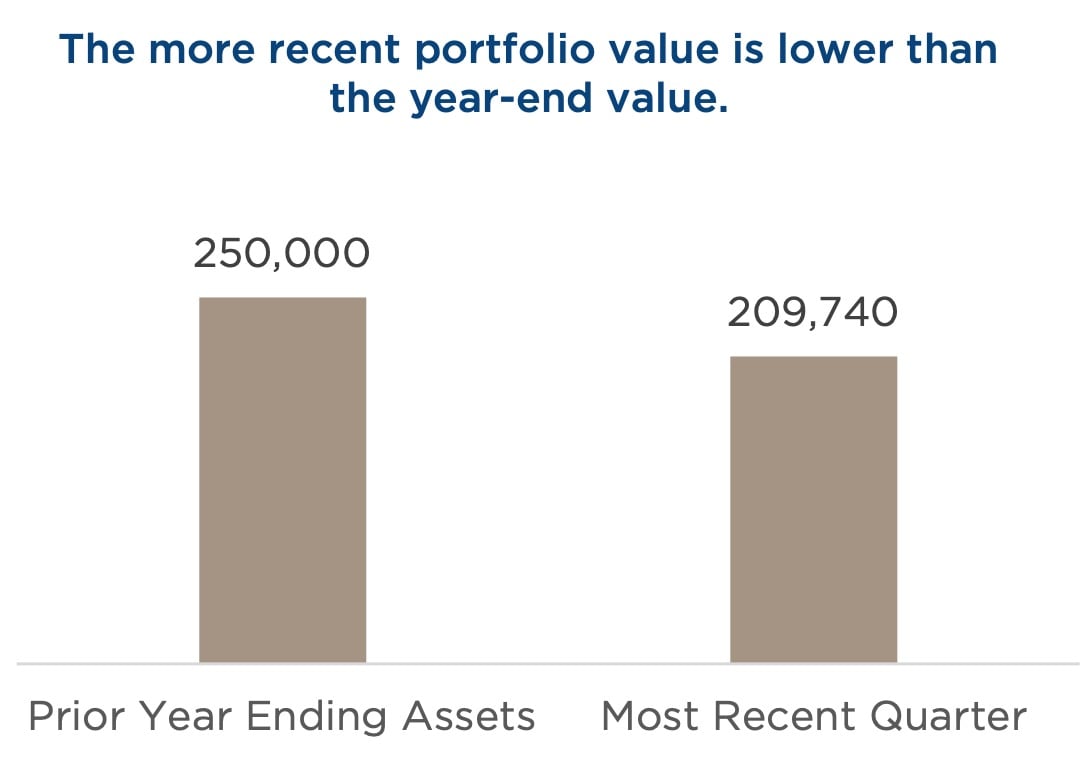
Another organization may choose a simple 5 percent annual spending policy. Determining the applicable date of market values can impact the sensitivity of spending levels to fast-changing market conditions, Terrell says. For instance, the organization may have targeted spending of $250,000 as of year-end, but the amount would be lowered to $210,000 if an additional rule considers a more recent asset value. The organization may choose to make the inverse true as well, specifying that if asset values on a defined date equal more than $250,000, spending may be raised. This could happen as the result of an unusually large rally or after the receipt of a large gift, for example.
Example C: Market Conditions
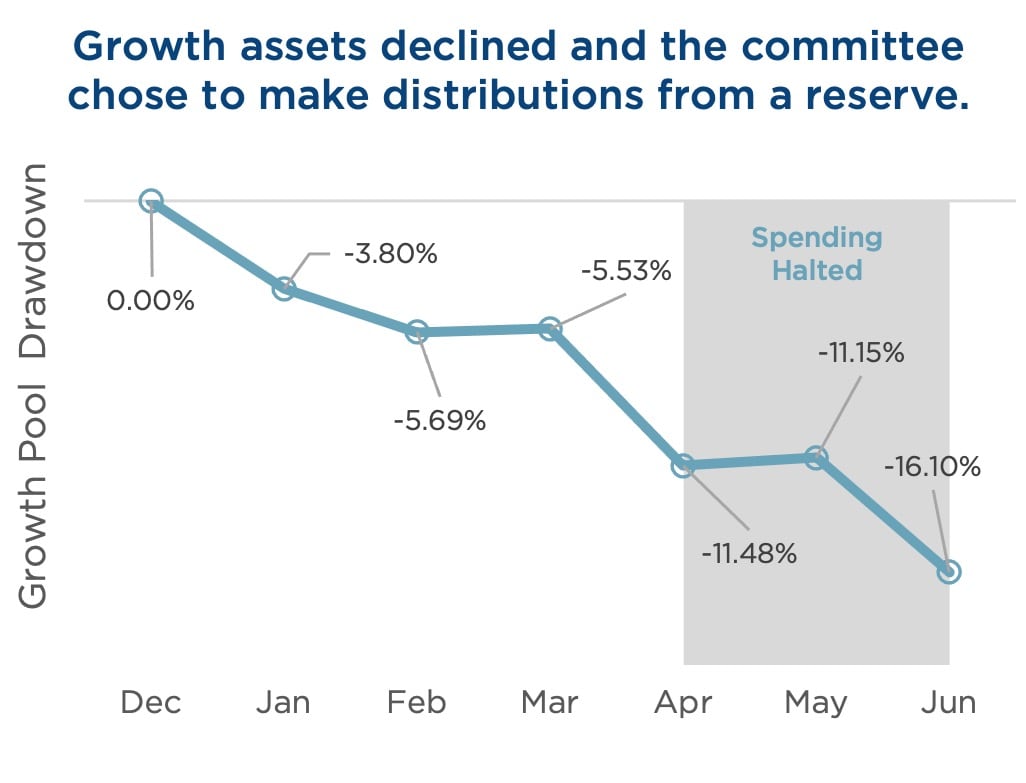
Some conditional spending policies may adjust spending levels when market performance meets certain thresholds or when assets rise above—or fall beneath—specific values. Another option is to temporarily halt distributions after a large enough decline in the portfolio, when assets fall below a reserve level. Some organizations will also choose to increase spending over time to address inflation.
When Markets Are Down
“No matter which policies are implemented,” says Verhaeghe, “every organization will have to consider its unique requirements. A private foundation might be subject to IRS rules, while a public foundation might have more flexibility. One organization may rely heavily on an endowment or foundation to cover its operational expenses, and another may have a mission that requires significantly more spending in a tough market.”
This is a common theme. Many endowments and foundations have a greater need for spending when markets are depressed. In fact, for some of these organizations, reducing spending in times of disruption will run contrary to the reason they exist—to support people, institutions, and communities, especially when they need it most.
“It’s not lost on me that telling endowments and foundations to spend less in a difficult economic environment is easy to say and hard to do,” Verhaeghe says. “But this is unlikely to be the only time that markets are volatile or down.”
His advice: “Stay committed to the mission. But also, as a long-term best practice, the more planning an organization can do, the more likely it is that its team will make good financial decisions, because planning helps create balance between immediate spending needs and long-term spending plans.”
Understanding that the organization will almost certainly face another unusual market makes a clear case both for robust planning and for conditional spending policy design. “With a defined spending policy that is formally documented in the organization’s IPS, decision makers are not simply reacting to portfolio growth or decline,” says Verhaeghe. “They’re making proactive decisions that help protect the organization’s ability to achieve its mission, both now and for the long run.”
As you plan for your estate, one important decision you’ll have to make will be your choice of trustee. This is also often one of the most challenging choices.
Your trustee holds legal title to the assets in your trust and has a responsibility to act in the best interests of the trust beneficiaries. They must follow the instructions in the trust document as well as the rules laid out by state and federal laws. Unlike a personal representative or executor who may serve for one to two years, a trustee may serve for a much longer term.
If you have a revocable trust, you will probably serve as trustee during your life, but you will also need to name a successor to take over after you die or if you become incapacitated. Many people wonder if they should choose a family member or close friend, or whether they will be better off with a professional trustee. Each of these options has its advantages and disadvantages.
Choosing Family or Friends as Trustees
A family member or friend may be more likely to understand your wishes and family dynamics. In addition, a family member may charge little or no fee. At the same time, they may lack the skills to carry out this role. If there are disagreements between the trustee and the beneficiaries, family relationships can be strained.
If the trustee is also a beneficiary, then the trust must be carefully drafted to avoid any adverse income or estate tax consequences. Finally, if the trust is intended to last for generations, the trustee will need a successor, or successors, to take over in the event of death or disability.
Choosing a Corporate or Professional Trustee
A corporate or professional trustee will have the expertise to manage the trust and handle the administrative details. They can also work with beneficiaries in a fair and steady manner. A corporate trustee will not die, which provides continuity.
One drawback is that a corporate trustee may charge a fee, while a family member may not. Furthermore, the trustee may not know your beneficiaries very well and may act more conservatively than you would have intended. However, this may be less of a factor if you choose a trustee with whom you have a relationship so that they understand your wishes and can carry them out.
Making the Decision
Your decision will depend on a variety of factors. In some cases, especially if the trust is large, grantors will name a family member and a corporate trustee as co-trustees to get the best of both worlds.
It is also important to consider the goals of the trust, along with its size, expected duration, and the types of assets it will hold. For example, a complicated trust that is expected to last for generations may mean that a professional trustee is more suitable. You should also consider whether you have an individual in mind whom you can trust completely, and how they would negotiate family dynamics.
As you make this decision, pay attention to some of the provisions in your trust that relate to your trustees. You may think some of the sections in the back of the trust are unimportant or are standard, boilerplate language, but these sections can have significant consequences. Read them and know what they entail.
You should review who has the power to remove trustees and appoint successors after your death. If you have multiple trustees, the trust should specify how decisions are made when trustees disagree. If you do choose a family member or friend, the trust should give that individual the authority to hire professionals to assist them.
Ultimately, your choice of trustee is a personal decision, and there is no one right answer for everyone. For this reason, it is important that you take the time to make this decision thoughtfully and intentionally. By making your wishes regarding your successor clear, you can help clear the path to a smooth transition for your beneficiaries.
It is common for businesses and nonprofit organizations to have large asset pools, like cash or operating reserves, that aren’t yet designated for a specific goal or need. Often, these asset pools have been set aside as rainy-day funds and have grown over time beyond their necessary size. Properly managed, these pools can swell to be a source of capital growth for an organization, but a surprising number of institutional asset pools (IAPs) remain highly conservative when they could be growing.
Typically, IAPs are managed by either an organization’s internal investment committee or a third-party advisor. In both scenarios, the portfolio manager aims to maximize earning power so that the asset pools are not losing value or simply sitting stagnant without growth.
For example, consider a privately owned business that has recently accumulated quite a bit of cash after two consecutive quarters of strong sales. The owners want to keep the money accessible to the company but are also interested in taking advantage of a current market dip to grow their assets over time. In this case, they may choose to manage the funds themselves, investing in stocks, bonds, and other assets of their own choosing, or assign management to an independent advisor.
Depending on the type of organization and the state in which it operates, each institution may or may not be subject to legal regulations regarding fiduciary responsibilities. But even if the organization falls outside the legal definition of a fiduciary, companies still have an ethical responsibility to their constituents to manage assets prudently, says Grant Verhaeghe, CAPTRUST senior director of institutional portfolios.
“Any person who works as a steward of an organization’s assets should be thinking about and learning best practices for institutional asset pool management,” Verhaeghe says. For institutions that use an internal investment committee for asset management, here are some best practices to consider.
Consider Investment
When considering whether to invest institutional asset pools, there is no one-size-fits-all threshold or standard investment strategy, says Verhaeghe. “Depending on the organization’s unique goals and liquidity needs, each one will use these pools differently and have different objectives,” he says.
Eric Bailey, head of CAPTRUST’s endowment and foundation practice, agrees: “The threshold will be different for every organization, but in general, if you think your organization could be earning a material amount of money through investment, then it’s a good idea to talk about investment strategies so you can put existing IAPs to work.”
For example, Bailey says, imagine a business has something like $10 million sitting on its balance sheet in a variety of places, currently earning zero dollars. Through investment, this business could potentially earn a return on its cash reserves. “Even small amounts can make a material difference to annual profit-and-loss statements,” he says. “The company could then deploy those earnings on a discretionary basis, for instance as bonuses or by hiring more people.”
What’s key is understanding both the upside potential and risks involved in IAP investment so that the organization can make informed decisions with appropriate short- and long-term perspectives.
Account for Time Horizons
Another best practice for IAP management is to consider time horizons for invested assets, or how quickly you might need to deploy the capital. Some asset pools will need to be spent in the next month; others in the next one to three years; and still others can sit in waiting for a longer period. Which asset pools will be good candidates for investment depends on the organization’s cash-flow needs and vulnerabilities.
As Bailey says, “One of the keys to managing IAPs is matching the money to the right time horizon to create the right investment strategy.”
A nonprofit, he says, may need a larger rainy-day fund of liquid assets that are easily accessible and safely stored, just in case donations diminish or the organization doesn’t receive a particular grant they were used to receiving. “These reserves are typically managed conservatively, with capital preservation at center of mind,” says Bailey. “They need to be liquid, safe, and readily available. But asset pools with longer time horizons may be good options for a little more risk, and you may potentially see a higher rate of return.”
Manage Risk
Evaluating how much risk to take with your IAPs depends on how a market decline would affect your organization both now and in the long-term future. Again, each institution will be unique. “The important piece is to fully consider the implications of potential growth or potential loss before you make IAP investment decisions,” says Bailey.
For example, Bailey says, consider a healthcare organization—a hospital that has issued municipal bonds to upgrade its equipment. The bond underwriters give the hospital a credit rating based on its debt, and the hospital will have debt covenants it must meet. “If investments drop too far in value because of a market decline, the hospital can be downgraded by credit rating agencies. This downgrade could cost the organization additional interest expense in future bond issuances or make their bonds less desirable,” he says.
A publicly traded company, on the other hand, will need to consider how investment gains and losses may impact its quarterly earnings statements and, therefore, its stock value.
“Investments on a balance sheet are naturally going to go up and down over time,” Bailey says, “and those changes will flow through to impact other areas of the organization. The critical element is understanding what areas will be impacted and how so that you can make the best possible decisions.”
At times, an investment committee or financial advisor may be managing institutional assets that have liabilities attached. In this case, Verhaeghe recommends organizations create risk models that explain the conditions under which it may be appropriate to take risk, and when it is not. Factors to consider include when the money will be needed, what the expected return will be, and how much risk the organization is able and willing to take.
Document the Process
“Regardless of whether the organization is considered a fiduciary, it’s a good idea to follow a sound process around your investment decisions and document each step,” says Verhaeghe. “That way, if anyone ever asks questions about what you chose or why you chose it, you have the answers.”
These answers may include articulating the organization’s financial needs, goals, and vulnerabilities; documenting practices in an investment policy statement; gathering regular reporting statements; or revisiting goals as the facts and circumstances change over time, Verhaeghe says.
“No two institutions are the same,” says Bailey, “There are dozens of different variables that will impact how each organization should be investing.” For instance, whereas a retirement plan will have a long-term time horizon and specific goal as it relates to each participant or beneficiary, a small, privately owned business may have the goal to maintain purchasing power of its operating reserves and potentially grow that purchasing power over time.
By following these practices, organizations that are independently managing their IAPs can deliver on their fiduciary responsibilities, whether legally mandated or not. However, for organizations that want assistance, managing institutional asset pools is an easy add-on to a trusted relationship with an existing financial advisor. Whichever path these institutions choose, they can be sure they are engaging in healthy financial practices to ensure long-term viability and, potentially, a healthy return as well.
The passage of the SECURE 2.0 Act introduced a range of retirement plan enhancements designed to bolster financial security for American workers. So far, however, most of its optional provisions are seeing minimal uptake. Taken at face value, slow uptake may seem discouraging, but it does not mean the act isn’t having an impact on improving financial wellness. Consider SECURE 2.0 as part of a bigger financial wellness snowball instead. Its power is likely to grow over time, especially as it converges with other financial technologies and trends.
“The lightbulb is turning on,” says Mike Webb, CAPTRUST senior manager of plan consulting. “Employers are thinking: There are so many other ways I can look out for people financially, beyond just pay and a retirement plan.” SECURE 2.0 helped kickstart those conversations and bring them into the spotlight.
Different Offering, Equal Impact
“Uptake of optional provisions is just one part of the story,” says Audrey Wheat, CAPTRUST senior manager of vendor analysis and strategic relations. “First, there are a number of mandatory provisions for which we can assume universal uptake. Second, it’s important to point out that plan sponsors and their vendor-partners are also exploring other avenues to offer financial wellness features outside the plan itself.”
For example, one optional provision offers the ability for employers to establish emergency savings accounts within retirement plans. These accounts allow non-highly compensated employees to contribute up to $2,500 of after-tax dollars.
Wheat says the overall sentiment about this provision is that’s its overly complicated and carries a heavy administrative burden. “Plan sponsors may not choose to integrate this provision, but they still realize they need to have an emergency savings option,” she says.
According to CAPTRUST research, some plans are choosing to offer stand-alone emergency savings programs instead. These programs often include payroll-deducted savings accounts with employer-sponsored financial coaching. The goal is to help employees build short-term financial security without modifying their retirement plan contributions or taking withdrawals, such as loans, from their plan balances.
“Sometimes, it’s easier to provide an alternative solution than to change the plan itself,” says Webb. Another example: Some companies now provide direct student loan repayment assistance instead of using SECURE 2.0’s student loan matching feature—another one of its optional provisions.
Cumulative Impact
Employers don’t need to overhaul their retirement plans to support financial wellness. Sometimes, simple tools and good guidance can be just as effective.
“When people have access to good information and tools, they’re able to manage their finances more confidently,” says Chris Whitlow, CAPTRUST senior director and head of CAPTRUST at Work, the firm’s financial wellness solution for institutional clients. “Confidence reduces financial stress today and helps people stay focused on the future.”
Whitlow says he sees employers integrating a range of third-party benefits and tools, from financial wellness platforms to artificial-intelligence-enabled budgeting tools to automated savings programs, in addition to SECURE 2.0 provisions.
“What’s really exciting is watching these different technologies and programs start to come together,” says Whitlow. “As that happens, we’re going to see financial wellness evolve much faster, and that’s going to create real, meaningful change for people.”
Webb agrees. “First, we saw the natural rise of auto-enrollment. Then the mandatory rise of auto-enrollment, automatic increases in deduction rates, emergency savings accounts, and the saver’s match, which—when combined—will add up to tremendous growth in retirement plan and other savings accounts in the future. All these layers on top of one another. The snowball is getting bigger, and it’s picking up speed.”
The Saver’s Match and a Savings Mindset
Webb says he is especially excited about the retirement saver’s match, a part of SECURE 2.0 that comes into effect in 2027. “The savers match has the potential to transform this industry as much as automatic enrollment and target-date funds did.”
The saver’s match is a government-funded matching contribution to an eligible employer-sponsored or individual retirement account. Through the savers’ match, the federal government will match 50 percent of retirement account contributions up to $2,000 for low- and middle-income taxpayers. Sponsor participation in the saver’s match is optional, so the success of the program will depend on two key factors: overall adoption rates and taxpayer education. Participants will need to elect to add a saver’s match account when filing their taxes.
“We will see a tipping point,” Webb says. “A lot of people have no savings at all. Suddenly, they’re going to have a retirement plan account that might have $10,000 in it within two years, and if we haven’t incentivized a savings mindset in them before that time, they’re going to want to withdraw that money to pay bills. Now’s the time to get ahead.”
Having a savings mindset means staying focused on long-term financial goals. The saver’s match and employer-sponsored emergency savings accounts are two ways to incentivize this type of long-term thinking. Having access to emergency savings might also help employees avoid withdrawing funds from their retirement plans.
“The truth is that most people who take loans out of their plans are taking smallish amounts of money—$1,000 to $3,000—that could easily come from emergency savings instead,” says Whitlow. “Participants may not be so tempted to take loans, hardships, and other in-service distributions if they have a separate pot of money for emergencies.”
Especially for early- and mid-career workers, withdrawing small sums can have detrimental long-term effects because they’ll miss out on compound earnings. “If employers can automate the emergency savings piece, employees are more likely to be in better shape, both in the near and long term,” says Webb.
Retirement Rich, Cash Poor?
According to Fidelity, the number of 401(k) millionaires rose 27 percent in 2024, rising from 422,000 to 537,000 people. These are historic numbers, but they’re likely to look less impressive over time as younger generations get an early start at saving.
“We talk so much about the state of retirement for baby boomers and Gen Xers,” says Webb. “What most people aren’t talking about yet is what this all means for Gen Z and Gen Alpha. If you’re in your early 20s right now with $10,000 in a retirement account, and you don’t touch it, with the compounding power of continued savings and earnings, you have the potential to be able to retire as a millionaire.”
“We’re going to see so many people who earned modest middle-class salaries retiring with seven-figure balances in their retirement accounts,” he says. “They may still be liquid-asset poor if they don’t have good guidance and education, but they will retire well.”
That’s one of the reasons financial wellness programs are critical, and it may help explain why employers aren’t rushing to integrate all SECURE 2.0’s optional provisions. “Most plan sponsors and recordkeepers see SECURE and SECURE 2.0 as parts of a bigger conversation about employee attraction, retention, and financial wellness,” says Wheat. The question employers are asking isn’t as simple as “Which SECURE 2.0 provisions should we offer?” Instead, they’re asking “What are our ideal financial outcomes for our workforce?” Then, they’re working backward to decide which means can help them achieve their goals. SECURE 2.0 is just one of the tools in the toolbox.
The first 50 days of President Trump’s second term have seen a surge of policy actions spanning a broad range of issues. While any one of these initiatives could serve as a stand-alone policy agenda for a president, this administration is ambitiously advancing multiple items through the policy funnel simultaneously.
The result has been a steady stream of headlines that has left investors navigating an increasingly complex and unpredictable landscape, akin to a multidimensional chess game. Capturing the most headlines over the past week has been the impending levy of tariffs on Mexico, Canada, and China. Here, we outline what we believe are the primary goals and potential risks of these rapidly evolving trade policy initiatives. We also highlight how economic uncertainty stemming from the crosscurrents of several policy shifts is influencing our investment decision-making process.
Figure One: The Policy Agenda Funnel
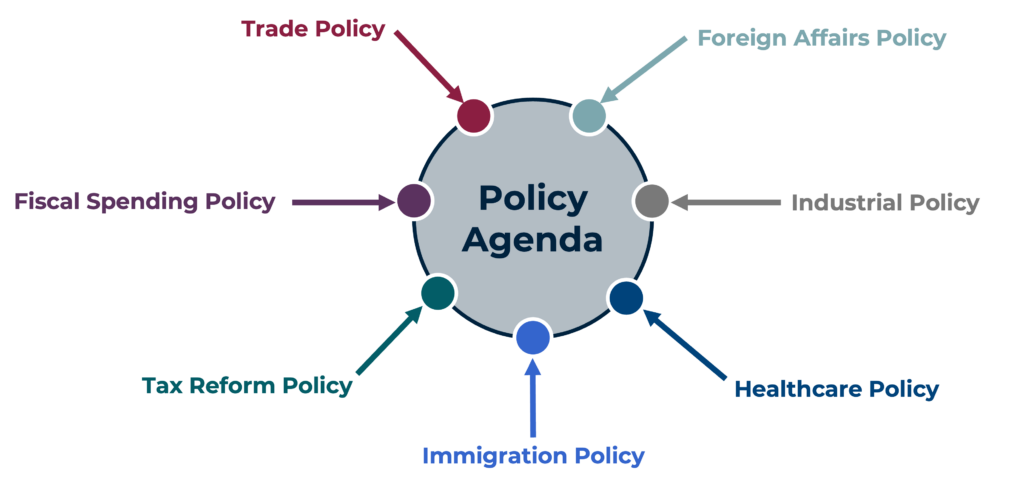
Source: CAPTRUST research. For illustrative purposes only.
Primary Goals
We believe the administration’s trade policy reforms are designed to pursue four main objectives.
- Reshoring and Foreign Investment: By making it more expensive to buy foreign goods, tariffs incentivize U.S. manufacturing. This has the potential to drive an increase in domestic and foreign investment into the U.S. For example, in the past week, we saw companies, including Apple and Taiwan Semiconductor, announce significant investments in domestic research and development and in semiconductor chip-making facilities.
- Balancing the Playing Field: The president strongly believes there are imbalances within existing trade relationships that create an unfair competitive advantage for other countries. He is seeking to counteract tariffs on U.S.-made goods and foreign subsidies for industries such as agriculture, forestry, and auto manufacturing.
- Creating Sources of Revenue: Tariffs are direct payments made to the U.S. government, which could improve our current fiscal condition. They could also potentially offset the cost of other proposed policy items, most notably the extension of the cuts included in the Tax Cuts and Jobs Act (TCJA). However, it is important to understand that the true revenue impact is far from certain, as tariffs and any potential retaliation could dampen economic growth conditions.
- Leveraging for Non-Trade Negotiations: Tariffs are a bargaining tool that extends beyond trade policy. They can be used to pressure foreign governments on issues such as border security, drug enforcement, and other geopolitical objectives.
Potential Outcomes with Meaningful Impacts
The immense scale, complexity, and importance of international trade mean that policy shifts introduce significant potential risks. This is particularly true at present, because the initial round of proposed tariffs targets nations that currently represent more than 40 percent of total U.S. annual imports. However, because these issues continue to be negotiated, the ultimate extent of impact on consumers, businesses, markets, and the economy will depend on the breadth and depth of actual imposed tariffs. We believe the most likely outcomes include the following.
- Profit and Inflation Pressures: In response to tariffs, companies can absorb the cost (placing downward pressure on profit margins), raise prices to consumers, or enact some combination of both of these actions. While higher prices may be viewed as inflationary, the market’s initial reaction—falling bond yields and increased expectations for 2025 Federal Reserve interest rate cuts—suggests they are currently being viewed as a one-time, short-term price adjustment rather than a sustained inflationary trend. However, depending on the length and magnitude of the trade conflict, shifting supply chains could serve as a longer-term inflationary influence.
- Economic Growth Headwinds: Initial market reactions to imposed tariffs suggest investors are more concerned with the potential impact to economic growth than with the short-term price impacts. The Yale Budget Lab estimates the economic impact of these tariffs would be a 0.6 percent reduction in real gross domestic product in 2025, leveling to a longer-term economic growth drag of 0.3–0.4 percent annually while in effect.
- Retaliation: Canada, Mexico, and China have all indicated they will retaliate with higher tariffs on U.S. goods. This unpredictable cycle of escalating tariffs creates greater uncertainty for businesses, increased complexity for global supply chains, and elevated market volatility for investors.
Investment Implications
In this uncertain and rapidly evolving environment, it is extremely challenging to determine specific investment implications with a high degree of confidence. Despite this uncertainty, what is becoming clear is that the decision-making landscape is being reshaped.
Some of the most important underlying economic assumptions that investors have historically modeled with confidence, such as trade relationships, security alliances, and free markets, are now being scrutinized and, in some cases, completely reset.
Although the final contours of the administration’s policy changes are far from certain, many of the fundamental factors that have shaped markets and investment outcomes for the past decade are now changing at an unprecedented pace and scale. These changes should not necessarily be viewed as bearish in the long term. Rather, changing assumptions are an indication that future winners may be different than past ones, and an uncertain transitional period is likely.
The two biggest questions the CAPTRUST Investment Committee is focusing on are “What bearing will this new environment have on U.S. technology leadership in global markets?” and “How will it influence unity and competitiveness in Europe?”
- America’s Global Tech Leadership: U.S. mega-cap technology giants have maintained a dominant position across the global equity landscape for much of the last decade. How could the changing policy environment affect their market position? The answer to this question will have an outsized impact on domestic markets going forward, given their current valuation levels and massive share of the overall U.S. equity market.
- The Unity and Competitiveness of Europe: European equity markets have been left behind by their U.S. counterparts, as their policymakers found comfort in the security the U.S. provided, and in cheap goods sourced from China. Europe may now be forced to become more self-reliant and more competitive, which could be the catalyst for real change. This, in turn, could drive potentially higher economic growth rates across the region, which has suffered from extremely low expectations, as reflected in depressed stock market valuations.
By any account, this is a historical moment. Investors are rarely faced with a true regime change, but the scale and speed of recent policy actions suggest that investors and businesses may need to adjust to a new set of economic conditions.
New environments can create risks—but also opportunities—for investors who adapt. The Trump administration has already demonstrated a willingness to employ unconventional negotiation strategies. While the ultimate outcome of various policy shifts is still unknown, what does appear evident is that market volatility is likely to persist as investors attempt to understand and adjust to this shifting economic landscape.
As financial advisors, we are paying close attention to fiscal policy outcomes. While we may experience short-term volatility as markets adjust to shifting policy, our core investment principles will not change: remain diversified, resist emotional decision-making, and maintain a long-term perspective to best capture the long-term compounding power of time.
The Fed’s September 2024 decision to start lowering the fed funds rate marked a big policy shift from recent years’ rising rates. Its effects will ripple through various sectors of the economy.
For the real estate market, lower interest rates generally mean good news. As the Fed cuts rates, mortgage rates tend to follow suit, although not always in perfect sync. Federal funds rate cuts have a direct impact on short-term interest rates. Other factors also influence mortgage rates, including long-term bond yields, inflation expectations, and each lender’s appetite for risk.
To understand the impact of easing rates, it’s helpful to look at this question through the eyes of two audiences: first-time homebuyers and existing homeowners.
While lower interest rates could encourage first-time buyers, home prices are near record highs and could remain prohibitive for some time. Home values have appreciated significantly since the beginning of the pandemic, so one or two rate cuts may not be enough to bring mortgage payments to a level where affordability meaningfully improves.
Existing homeowners have benefited from price appreciation, adding more than $14 trillion to their home equity. Having locked in ultra-low mortgage rates during the pandemic, these owners are unlikely to sell. Yet as rates fall, they may seek to unlock value by borrowing through home equity lines of credit (HELOCs). This form of borrowing, which slowed as interest rates climbed over the past few years, could help fund renovations, investments outside the home, and debt consolidation.
In his remarks over the past few years, Fed Chair Jerome Powell has used the word recalibration many times, suggesting that this easing cycle is about returning rates to levels that neither restrict nor overstimulate the economy. This begs the question: How fast and how far will the Fed cut rates? Fed economists will be watching the economic data for signs of recession, which would likely prompt faster or deeper rate cuts. At the same time, they are mindful of the possibility that inflation could reignite, which could slow its rate-cut trajectory.
Of course, housing is not the only sector that stands to benefit from falling interest rates. A lower-rate environment can reduce variable-rate debt on credit cards and auto loans, opening room in budgets for more consumer spending. Businesses may also step up their capital investments and hiring plans.
A Roth conversion involves transferring funds from a traditional retirement account—such as a 401(k), 403(b), or individual retirement account (IRA) funded with pre-tax dollars—into a Roth IRA.
Why would someone consider a Roth conversion? The biggest benefit lies in the tax treatment of the converted funds. Once the funds are in the Roth IRA, future growth of those assets is tax-free. Withdrawals in retirement are also tax-free, assuming they meet certain criteria. As with any strategy, there are important considerations to keep in mind.
When you convert funds to a Roth IRA, the amount converted is taxable income in that tax year. For example, if you convert $100,000 from a traditional IRA to a Roth IRA, that $100,000 will be added to your taxable income in the conversion year.
Converting large amounts can result in a significant tax bill and may push you into a higher tax bracket. Even so, using retirement funds to pay taxes may make sense for those looking to convert large IRAs to reduce their future required minimum distributions (RMDs).
The timing of your Roth conversion matters too. Generally, it’s a good idea to convert when your income is lower—for example, after you’ve retired and before you begin drawing Social Security. You may also choose to convert over the course of several years to spread out the tax impacts. But if you can get comfortable with these considerations, a Roth conversion can provide you with benefits beyond tax-free growth and withdrawals. Some of these benefits are:
- Tax diversification. Having both traditional and Roth accounts allows you to manage your tax liability in retirement. For example, if your income in a given year is higher than expected, you can withdraw from the Roth IRA without increasing your taxable income.
- No RMDs. Traditional IRAs and 401(k)s require you to begin taking RMDs at age 73. Roth IRAs have no RMD requirement during your lifetime. With a Roth account, you have more control over your retirement withdrawals and can leave the funds to grow for your heirs.
- Benefits for heirs. Roth IRAs can be passed on to beneficiaries, who can inherit the account income tax-free. This means your heirs can enjoy the tax-free growth and withdrawals if the Roth IRA has been held for five years or more—a significant advantage, especially if your beneficiaries are in a higher tax bracket.
As always, you should consult your tax and financial advisors and consider your unique situation and goals.
Life is uncertain, and it’s often these unknowns that cause the most worry—for instance, the future of Social Security benefits.
Financial planning can help alleviate some of these worries by providing clarity and by making sure your Social Security benefits are appropriately accounted for in your long-term financial strategy.
How Social Security Began
Congress established the Social Security program to provide a reliable fixed income for retirees. In the beginning, there were more workers paying their share of the payroll tax—now known as Federal Insurance Contributions Act (FICA) tax—into the plan than there were retirees receiving benefits, so excess funds were used to create a trust to house the growing surplus.
From 1984 to 2009, the total amount of money gathered from FICA taxes exceeded the amount of money that the Social Security program was paying in benefits, and funds accumulated in the trust.
However, by 2010, things changed. The number of retirees receiving benefits was higher than originally expected, likely due to high unemployment rates and an aging population that collectively retired after the 2008–2009 financial crisis. The fund began paying out more than it was receiving. To meet its financial obligations, the Social Security program needed to use a portion of its trust to cover the deficit.
Social Security Changes, Past and Future
Multiple adjustments have already been made to the program, like increasing the Social Security wage base limit, which is the amount of income subject to Social Security taxes. Another change redefined full retirement age, which is the age when a person can begin collecting their full Social Security benefits. Changes such as these began in 1983, and small adjustments continue to be made.
Some likely future adjustments could include another change to full retirement age or further adjustments to the amount of income that is subject to Social Security taxes. Both major political parties have proposed these changes, and other strategies, as solutions to shore up any gap in benefits. Although privatization of the Social Security trust has been proposed a few times over the years, recently, it has not been a major topic of discussion. We believe privatization is an unlikely change.
2025 Social Security Changes
The Social Security Fairness Act, signed into law on January 5, 2025, effectively repeals the Windfall Elimination Provision (WEP) and Government Pension Offset (GPO) rules. This means that individuals who were previously subject to WEP and GPO may benefit from an increase in their Social Security benefits. However, the timeline of when these changes will take effect has not yet been determined by the Social Security Administration.
What impact will this change have on the viability of Social Security? Likely, it will speed up the timeline for when Congress must make Social Security decisions, but it won’t change how likely or unlikely those changes are.
The Viability of Benefits
When people talk about potential Social Security changes, they often express concern that the program will be eliminated, and they won’t receive the benefits they’re counting on.
Even in the unlikely event that Congress doesn’t make further adjustments, and the trust fund portion becomes depleted, Social Security benefits won’t vanish overnight. Benefits would be reduced but not eliminated entirely.
According to a recent study by the Social Security Trustees, by 2035, even if the fund were depleted, Social Security would still be able to pay 83 percent of scheduled benefits from the incoming payroll tax portion of the fund. In 2098, it would still be able to cover 73 percent of scheduled benefits.
In other words, even if Congress chose to do nothing at the time to correct the depletion (a highly unlikely strategy for any Congressional delegation), the program would still be able to pay a sizeable portion of benefits for multiple generations.
Regardless of what happens in future legislation, planning for Social Security benefits is an important part of building your retirement income plan. To prepare for a range of potential futures, talk with your financial advisor. They can help you model different scenarios and stress-test your plan against outcomes like a reduction in benefits. Knowing you’re prepared for whatever may happen can help provide perspective.
When she was in her early 40s, Schooley, now 63, launched a career in the maritime industry after more than two decades working in hospitality. She’s now the senior captain of a ship for a daytime tour company in Seattle, Washington.
“It was a huge leap to go from providing the waitstaff for events to being responsible for the safety and well-being of a ship, the crew, and hundreds of passengers,” says Schooley.
She found the perfect fit for her second act, but the journey to a new career was turbulent at times.
Learning to Serve
Schooley, the youngest of six children, was introduced to hospitality at a young age.
Her father was a long-haul truck driver. Her mother worked as a waitress at the revolving restaurant in Seattle’s famous Space Needle, the iconic landmark with panoramic views of the city and beyond.
Schooley and her siblings occasionally accompanied their mother to work. “We’d do our homework in the break room from the 600-foot level,” she says.
Schooley followed in her mother’s footsteps, working as a server at several restaurants, including one her parents owned for a few years.
Eventually, her mom started her own business, Always at Your Service, which provided trained service staff for parties and other occasions. It was a family affair. Schooley and her siblings helped with every aspect.
“We took care of staff and staging for everything from intimate dinners for two to events with 800 people at large venues,” she says. “We worked at weddings, holiday parties, corporate parties, and team-building events, as well as on private yachts and daytime cruise boats.”
Their customers included corporate executives, bureaucrats, and wealthy entrepreneurs. The business took off during the late 1980s and early 1990s. “People who worked for Microsoft in Redmond, Washington, created a ton of business,” she says.
Keeping Her Head Above Water
Throughout her 20s and 30s, Schooley worked nights, weekends, and holidays while also raising two daughters on her own. “My hours were all over the place,” she says. “There were no set workdays or benefits to the job. I was running from one event to another, making sure staff showed up.”
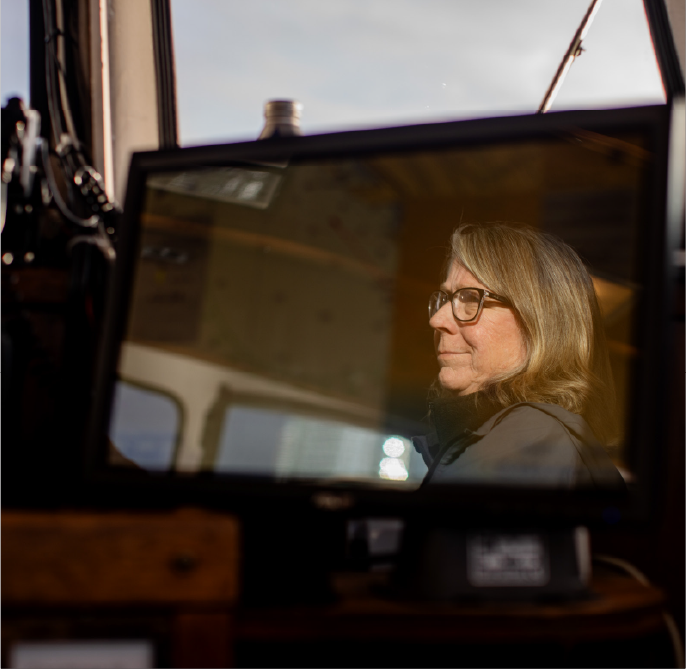
Working at the company and being a mom was exhausting, but her siblings would help with babysitting when they weren’t pitching in at the family business.
To escape the pressures of work, Schooley went out on the water. “I had a little motorboat that I could tool around in with my daughters.”
Schooley developed a love for boating when she was a child, during a trip to a lake with family and friends. “I remember the first time someone held me while skiing,” she says. “I have a vivid memory of the joy of the water.”
In 1998, Schooley took over running the business when her mother retired. That same year, she got married and moved with her husband, Pete Sandall, to an area of Seattle where it was difficult to keep her boat—so she sold it.
But she missed being on the water and, after a few years, she started thinking about ways to subsidize her hobby.
Charting Unfamiliar Territory
There was a Seattle Maritime Academy near her home. “One day I was driving by, and I pulled in,” she says. “I asked them what it would entail to get a license to run a little boat.”
The staff explained the cost and time involved. “I enrolled that same day,” she says. “I just wanted to dip my toe in to see what it would take.”
Her goal was to get a license to run a small commercial boat offering charters for up to six passengers, but academy personnel recommended she get a master’s license instead—one that would allow her to operate a vessel of up to 100 gross tons.
The test was similar, but there were key differences involving the size of the boat and the sea time she would need before she could apply for a license. Sea time is the number of hours a person has spent working on a vessel.
Training included an 80-hour course that would prepare her to take the licensing test. This training was broken into three parts: learning the rules of the water, charting courses, and studying federal regulation codes that pertain to maritime law.
Schooley was in a class with crab fishermen from Alaska, yacht delivery people, a water taxi service operator, and an employee of Argosy Cruises, which offers sightseeing tours on Elliott Bay, Lake Washington, and areas of Puget Sound.
After she passed the course, she worked for Argosy Cruises to earn her required sea time, which was the equivalent of 365 eight-hour days. “I already had some sea time from catering events on private yachts, but I still needed a lot of additional work,” she says.
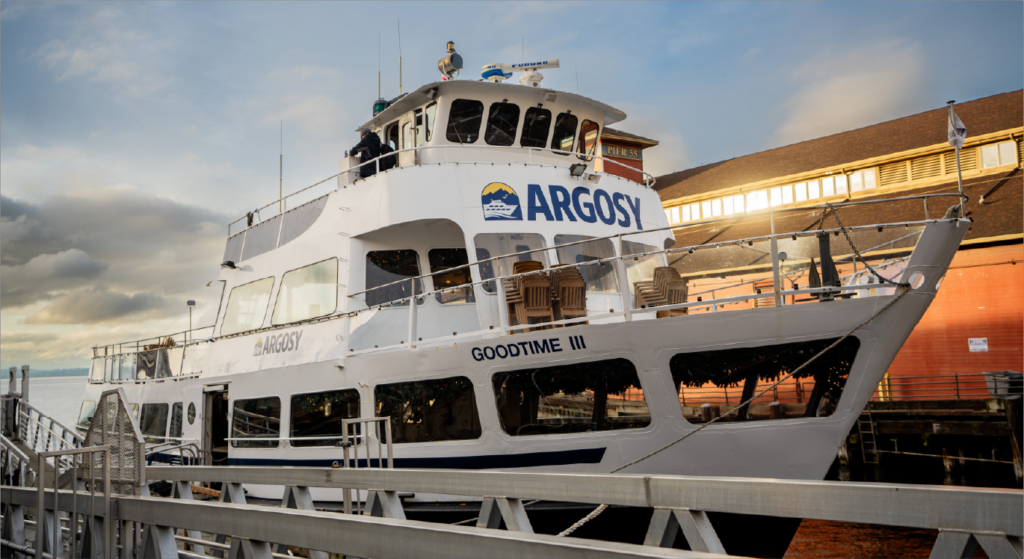
Steering Her Career in a New Direction
In 2004, Schooley started work as a deckhand for Argosy Cruises, where she learned the mechanics of maritime diesel engines, radio communication, how to raise and lower fenders, basic knots, and line-handling skills for securing the ship.
“I had to learn to safely tie up a vessel, securing it to the dock with primary lines,” she says. “I had to draw a schematic of the vessel, with the details of everything from the hatches and holes to electrical equipment and the lifesaving equipment onboard.”
There were times she doubted her new direction. “When I started as a deckhand, there was a horrible storm that came through with 40-mile-an-hour winds. It got rougher and rougher, to the extent that a refrigerator fell off the wall. I really did stop and wonder if this was the career for me.”
She couldn’t afford to quit her hospitality job while she was taking the class and doing various jobs on the ship, so she continued to run the family business. “I worked 60 to 80 hours a week,” she says. “It was rough.”
Also, there was a lot to learn about driving on water. “To become a captain, you have to know how to safely navigate a ship while managing a crew,” she says. “You have to pilot the vessel in all kinds of weather conditions, including winds, fog, and rain. I learned to drive by instrument with no visibility. The training was much harder than I expected.”
In 2005, Schooley got her 100-ton master’s license and began working full time for Argosy Cruises.
She decided to close the family business. “It was difficult to end that chapter,” she says. “But I felt like I was on two treadmills at the same time, and I had to jump off one.”
Landing in an Important Role
As a senior captain, Schooley can pilot all the ships in the company’s fleet. She is currently in charge of the 125-foot Salish Explorer, Argosy Cruises’ largest ship. “This just became my baby,” she says. “Every year, we switch to a different boat.”
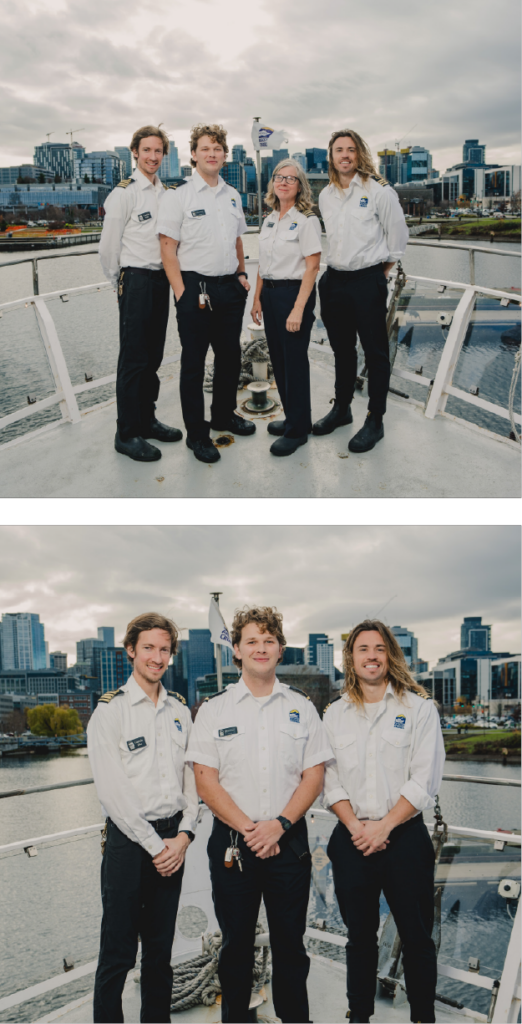
“The vessel can carry more than 500 passengers, but we usually only take about 200 to 300 passengers per trip in peak season,” she says. During the summer, she’s in charge of six one-hour cruises a day on Elliott Bay.
“When I’m driving the ship, I’m focused on navigation, communication, and visibility,” she says. “I’m monitoring three radios. I’m constantly watching everything, including ferry traffic, recreational vessel traffic, and fishing boats.”
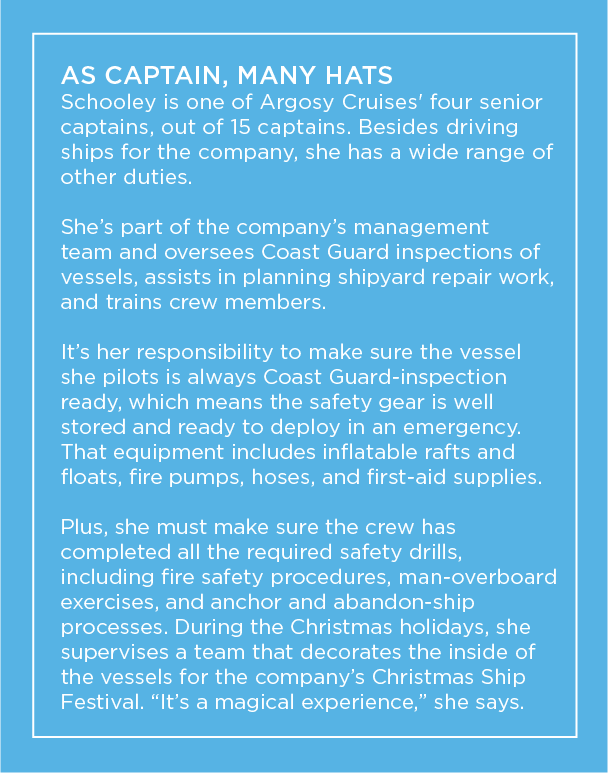
The ship has five crew members, one of whom is a senior deckhand. The deckhands must check in with her regularly. She also watches the cameras around the ship to check passengers’ safety.
“Every single person must carry their weight,” she says. “It’s a well-oiled machine. As a ship’s captain, you have to trust yourself, trust your crew, and trust your instruments. It’s a massive amount of responsibility, but I have crew members who help manage the vessel.”
Running a Tight Ship
Schooley still uses her well-honed hospitality skills. “If we have a private chartered cruise with caterers,” she says, “I make sure all the elements come together at the right time, including the catering service, music, and decorations.” She even officiates weddings occasionally.
Schooley’s husband says the maritime career combines his wife’s hospitality skills with her love for being on the water.
“When she’s in the wheelhouse, she’s clearly the captain,” Sandall says. “There’s no messing around. She’s got radios, and she’s on the ball, looking around.
“She’s in charge,” he says. “It’s impressive—all the hats she has to wear.”
Tricia Nielsen, a friend, former colleague at Argosy Cruises, and classmate at the maritime academy, says Schooley runs a tight ship in a supportive way that makes crew members feel appreciated, so they strive to do their best. One key to her success is that she takes the time to build relationships, Nielsen says.
At this stage of her life, Schooley says she’s exactly where she wants to be. “I’m happy being on the water, and I’m happy being around other people who love working on boats.
“Every day I go to work is a gift,” she says. “I have the best office in the world. The only regret I have is that I didn’t do it sooner.”
By Nanci Hellmich
Nanci Hellmich, an award-winning multimedia reporter, covered myriad topics for USA TODAY for more than 30 years. Now she writers for AARP, encore.org, and other organizations. She’s been named a top online influencer on weight loss and nutrition and has appeared on numerous television shows including NBC’s TODAY.
A fiduciary is a person or organization who prudently takes care of money or assets for another person or organization. Under the Employee Retirement Income Security Act of 1974, also known as ERISA, retirement plan sponsors are fiduciaries of their retirement plans. This means they are legally bound to act solely in the best interest of their plan participants. Fiduciaries who fail to fulfill that duty can face penalties and personal liability for plan losses.
Topics covered include:
- How you can identify plan fiduciaries;
- Four critical fiduciary responsibilities;
- The potential consequences of a fiduciary failure;
- Fiduciary liability reduction strategies and tactics; and
- How to differentiate between the two Department of Labor (DOL) fiduciary correction programs.
Additional CAPTRUST Resources:
Fiduciary Best Practices for Plan Sponsors Slide Deck
The Importance of Fiduciary Training
For a copy of the transcript, click here.
Our 2024 series:
Close
Close
"*" indicates required fields
Close
"*" indicates required fields
Close